Category: Global Tech Trends

  • Gemini 3.8 Flash Launched: 3 Reasons Why Real Costs Are Climbing 40% Despite Identical Pricing

    Gemini 3.8 Flash Launched: 3 Reasons Why Real Costs Are Climbing 40% Despite Identical Pricing

    Key Takeaways

    • Google unveiled Gemini 3.8 Flash just weeks after releasing 3.7 Flash.
    • Google said 3.8 Flash “works harder” by running more reasoning steps and repeatedly calling tools on complex tasks.
    • Launch pricing is identical to 3.7 Flash: $0.75 per million input tokens and $3.75 per million output tokens.

    An analytical news brief examining a new model with identical headline pricing but a fundamentally different real-world cost structure, from a developer and product perspective. The practical takeaway: model adoption decisions should weigh token-usage growth, not just the price sheet.

    Table of Contents

    Gemini 3.8 Flash arrived just weeks after 3.7 Flash. The published price sheet is unchanged: $0.75 per million input tokens and $3.75 per million output tokens. Yet measurements show that running the same task drives bills up by nearly 40% on average. Here’s why the listed rate can mislead.

    What “Works Harder” Really Means

    Google described Gemini 3.8 Flash with the phrase “works harder.” Unpacked, that combines two changes: it runs multiple internal reasoning steps on complex requests, and it repeatedly calls tools to review its own output.

    According to Artificial Analysis, per-task output tokens rose roughly 30% versus 3.7, and average turn counts climbed across agentic benchmarks — so a price that looked flat-rate ended up behaving like pay-per-use. That’s why Google officially warned about “possible increases in token usage.”

    Same Rate, Different Real Cost — Gemini 3.8 Flash Comparison

    Item 3.7 Flash Gemini 3.8 Flash
    Input rate (per 1M tokens) $0.75 $0.75
    Output rate (per 1M tokens) $3.75 $3.75
    Average output tokens per task Baseline ~30% increase
    Agentic eval turn count Baseline Increased
    Real per-task cost Baseline ~40% increase
    Lowest price at intelligence tier — Per Artificial Analysis

    As the table shows, the rate column is empty. What changed is the amount of tokens the model burns on its own. Google sets the price, but how the model solves the task ultimately decides the bill.

    What Practitioners Should Check Before Adopting Gemini 3.8 Flash

    From a practitioner’s standpoint, the most meaningful point is that the second half of the equation “rate × token volume = cost” is hard to control. Token volume is decided inside the model, so it can’t be fully suppressed by prompt tweaks alone. It’s safer to verify the following first.

    Pull the average output tokens per task and monthly totals from existing API call logs. Run sample tests with 3.8 Flash on the same inputs to measure how much output-token volume grows. Keep cost-sensitive workloads (summarization, classification, routing) on 3.7 Flash. Run A/B evaluations to confirm numerically that quality gains justify the cost increase. Different pricing tiers may apply depending on Fairwind Program eligibility, so revisit your contract terms.

    Where Gemini 3.8 Flash Stands in the Industry

    Artificial Analysis classified Gemini 3.8 Flash as “the lowest measured price at that intelligence level,” meaning the lowest cost for its quality tier. Aigora.ai CEO John Ennis called it “Opus 5-level coding quality at a much lower cost and faster speed.” The crux of the market reaction is that where Gemini 3.8 Flash sits against Anthropic’s Opus line — and whether it truly wins on token efficiency — needs to be examined separately.

    Google recognizes this too. It will continue offering 3.7 Flash for developers who want to minimize token consumption. With both available in the API, the premise that “the new model is always right” doesn’t hold. From this perspective, this launch should be read less as a trigger for wholesale model swaps and more as a signal to reset routing policy.

    What to Try Right Now

    • Pull average per-task output tokens and monthly token totals from your current API call logs.
    • Run 100 prompts of the same kind through 3.8 Flash to measure the output-token increase rate.
    • Build an A/B scenario where humans can evaluate whether quality differences justify the cost increase.
    • Define a routing policy that sends cost-sensitive workloads to 3.7 Flash and quality-sensitive jobs to 3.8 Flash.
    • Confirm Fairwind Program applicability and additional terms with the contracts team.

    Practical Application Points

    • Identical rate sheets don’t mean identical costs. Your actual bill is proportional to the tokens the model consumes.
    • Workloads with large output-token footprints see the biggest cost inflation on 3.8 Flash.
    • Because 3.7 Flash remains available, partial routing is safer than a full migration to the new model.
    • If you can’t numerically prove that quality gains justify the cost increase, it’s better to delay adoption.

    Frequently Asked Questions

    Is Gemini 3.8 Flash more expensive than 3.7?

    The rate is identical: $0.75 per million input tokens and $3.75 per million output tokens. However, because per-task token consumption has increased, measurements show bills rise by roughly 40% on average.

    Why does token usage increase in the same model family?

    Google explained that Gemini 3.8 Flash runs repeated reasoning steps on complex requests and makes multiple tool calls. It’s designed to work harder internally, so output tokens and turn counts both grow.

    Can I keep using 3.7 Flash?

    Yes, Google announced it will continue offering 3.7 Flash. A hybrid setup is possible: send token-efficiency-critical tasks to 3.7, and reserve 3.8 for jobs where quality and speed matter more.

    What is the Fairwind Program?

    It’s a new Google program launched alongside Gemini 3.8 Flash. Pricing conditions may vary by eligibility, so check the terms and scope before adoption.

    The essence of this announcement is not “a smarter model” but “a model that does more work for the same price.” Since Google itself warned about possible token-usage increases in the original Verge report, model choice should be driven by usage logs, not the price sheet.

    Reference Source

    This article was prepared after checking the following original source: The Verge — Google says its new Gemini 3.8 Flash model 'works harder' but might cost more
  • Pivotal CEO Change After 4 Years — 3 Signals for eVTOL Commercialization

    Pivotal CEO Change After 4 Years — 3 Signals for eVTOL Commercialization

    Key Summary

    • Pivotal CEO Ken Karklin has stepped down this week after more than four years in the role.
    • Pivotal’s official position is that Karklin is “pursuing new endeavors.”
    • His successor is Mike Ross, an aviation industry executive who joined the Pivotal board in November 2025, taking on the role of interim CEO.

    This is not a routine personnel move. It is a leadership change at a flagship American startup arriving at the moment the eVTOL industry shifts from prototypes to commercialization and regulatory execution — an issue-driven analysis of the strategic and industry signals behind the transition.

    Table of Contents

    Pivotal CEO Change After 4 Years — 3 Signals for eVTOL Commercialization

    The fact that Ken Karklin stepped down from the Pivotal CEO role became public on September 1, but signals of the move had been circulating for a month or two. Back in November 2025, when aviation veteran Mike Ross joined the Pivotal board, industry observers were already saying, “The next move is a CEO lineup adjustment.” The fact that the Pivotal CEO baton is passing from someone who held the seat for more than four years to a new board member of less than a year itself reads as a signal that the company has entered a new phase.

    Pivotal’s official position is measured. The entire statement is that Karklin is “pursuing new endeavors.” According to TechCrunch’s report, his successor is Mike Ross, who joined the board the same month and now takes the interim CEO seat. The two words most frequently cited at the moment of the Pivotal CEO change are “stability” and “regulatory readiness.”

    Four Years of Track Record: Up to the Helix Commercial Launch

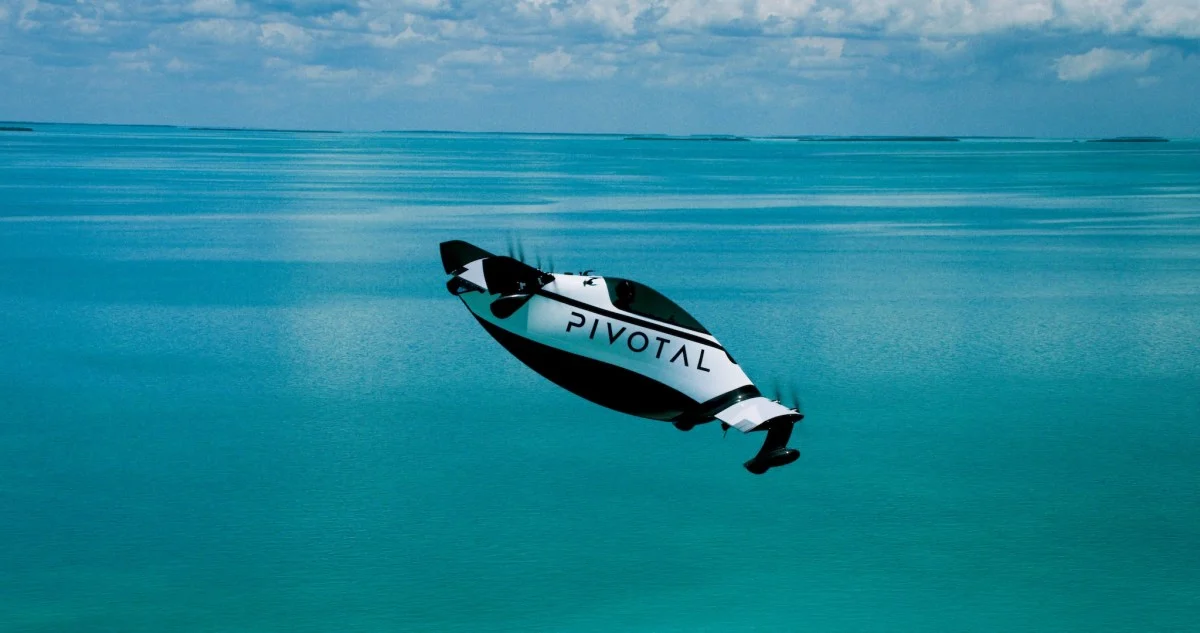
    The biggest achievement of Pivotal during Karklin’s four-year tenure as CEO is undoubtedly the commercial launch of the Helix. It is a lightweight single-seat electric eVTOL that requires no pilot’s license and carries a starting price of roughly $200,000. That price point is rarely seen in the existing personal aircraft market. The light sport aircraft market typically runs in the $50,000 to $150,000 range, but the Helix’s positioning is distinctly different because it bundles vertical takeoff and landing mobility into that price.

    The part that stands out to me is the regulatory hook of “no license required.” Under U.S. FAA rules, Light Sport Aircraft (LSA) do not require a separate pilot’s license, and the Helix falls into that category. In other words, even before the Pivotal CEO change, a reasonable interpretation is that the company’s chosen strategy was to “minimize regulatory barriers to mass-market entry.”

    Model Generation/Stage Seating License Expected Price
    Helix (current generation) 3rd gen — commercially available 1 seat Not required Approx. $200,000
    Helix 4th generation Next gen — roadmap stage 1–2 seats (expected) Reclassification possible Undisclosed
    BlackFly Separate lineup — development ongoing 1–2 seats Varies by regulatory stage Undisclosed (estimated premium)

    Why a Pivotal CEO Change Right Now

    The eVTOL industry has clearly shifted from the prototype and demonstration flights of the early 2020s to a commercialization and certification phase in 2025–2026. Fellow American companies such as Joby Aviation and Archer Aviation have unveiled certification testing and delivery timelines at similar junctures. If the Pivotal CEO change is read as a routine personnel move, it means the company is squarely facing this shift in the industry cycle.

    What stands out from a practitioner’s perspective is that Mike Ross took on the acting CEO role roughly 10 months after joining the board. Interim CEOs are typically brought in from outside, but having a board member who already knows the company step straight into the CEO seat signals an intent to project “continuity of a validated strategy” to the outside world. In his official statement, Ross referenced a “safety-, engineering-, and accessibility-focused disciplined approach,” making it clear he intends to carry the existing direction forward.

    Mike Ross Profile and the Next 12 Months

    Ross’s aviation industry career is confirmed through his official biography, but going only by what the company has disclosed, the most accurate description is “an aviation industry executive with proven execution capability.” Three items are emerging as his near-term priorities: commercializing the 4th-generation Helix, organizing the BlackFly lineup, and negotiating certification with regulators.

    More fundamental than the technical details is whether the 4th-generation Helix can retain the “no license required” category. As battery density, automated emergency landing, and collision avoidance technologies step up one tier at a time, the FAA could naturally revisit the license requirement. This point is likely to be the biggest variable the company will need to resolve after the Pivotal CEO change.

    Key Issues at a Glance

    • Whether the Helix’s “no license required” category can be maintained through the 4th-generation model
    • How the commercialization timing of the BlackFly lineup affects the Helix’s sales momentum
    • How Pivotal’s investment priority shifts within Larry Page’s Alphabet and subsidiary structure

    Reading a personnel change as merely a personnel change means missing half the story. The sequence in which the board accepted Karklin’s resignation and seated Ross as interim CEO in the same month is itself a clear message that the company has chosen an “insider-driven next phase.” On the other hand, compared with CEO change cases at other companies backed by large investors, in hard-tech fields like eVTOL, the shift from a “technology CEO” to an “operating CEO” is almost a required course.

    What to Do Right Now

    • Regularly check Pivotal’s official channels for spec change announcements on the 4th-generation Helix
    • Subscribe via RSS to updates on FAA Light Sport Aircraft (LSA) regulatory changes
    • Mark the certification timelines of competitors in the $200,000 personal eVTOL segment (Joby, Archer) on your calendar
    • Save any separate reporting or test flight videos of the BlackFly lineup as comparison material

    Frequently Asked Questions

    What is the reason for the Pivotal CEO change?

    Pivotal has publicly stated only that Ken Karklin is “pursuing new endeavors.” The dominant outside analysis is that as the eVTOL industry enters a commercialization phase, leadership that emphasizes operational and regulatory experience has become more important.

    Does the Helix require a pilot’s license?

    Yes — the current-generation Helix falls under the FAA Light Sport Aircraft (LSA) category in the United States and does not require a separate pilot’s license. However, for the 4th-generation model, regulatory reclassification is being discussed due to changes in weight and speed.

    What is the relationship between Pivotal and Larry Page?

    Pivotal is an eVTOL startup personally backed by Larry Page. It operates independently from Alphabet’s portfolio, and the investment structure itself is not publicly disclosed.

    The Pivotal CEO change is an event where “why this timing” matters more than “why this person.” With the 4th-generation Helix roadmap directly tied to next-quarter commercial momentum, whether Ross’s interim period leads to a permanent appointment or serves as a bridge to a new external hire is likely to be decided within 2026. The outcome will determine the next name for the Pivotal CEO role.

    Source Reference

    This article was written after reviewing the following source: TechCrunch — Larry Page’s flying car company Pivotal loses its CEO

  • Claude 5.1 Price Cut of 25–45% — The Structural Shift Behind Eliminating Cache Fees

    Claude 5.1 Price Cut of 25–45% — The Structural Shift Behind Eliminating Cache Fees

    Key Summary

    • The Verge reports that Anthropic has simultaneously launched two new AI models: Fable 5.1 and Mythos 5.1
    • Fable 5.1 is priced approximately 25% lower for general tasks and up to 45% cheaper for complex agentic work
    • The core of the price reduction lies in eliminating fees on already processed and stored cache data

    An analysis article that frames the new model launch along two axes—price competitiveness and safeguard redesign—and interprets the structural significance of the cache fee cut and the broader industry debate over the safety-performance balance from a practitioner’s perspective

    Table of Contents

    Claude 5.1 has been unveiled with concrete numbers—a 25–45% price reduction. According to The Verge’s report, Anthropic released two models, Fable 5.1 and Mythos 5.1, on the same day, and the core of the price cut lies in the structural elimination of cache data fees.

    Anyone who has run agentic workflows will immediately grasp the significance. The structure in which token costs accumulate when repeatedly passing the same context is genuinely heavy. The pricing change in Claude 5.1 strikes precisely at that point. The company announced price drops of approximately 25% for general tasks and up to 45% for complex agentic work—a result of reducing fees on already processed and stored cache data.

    To understand how the cache fee reduction changes practical work, it means the margin structure of RAG pipelines or multi-turn agents with many repeated calls can shift. The math now works out to running more calls with the same budget.

    The changes on the safeguard side are more subtle. Fable 5.1 ships with refined safeguards that lower the blocking probability for routine cases like “basic biology questions.” Mythos 5.1, on the other hand, maintains the same restrictions in the biology domain as the previous model. The fact that both models were released on the same day is significant in itself. It amounts to Anthropic explicitly demonstrating a dual policy of “loosening capability while keeping high-risk domains tightly controlled.”

    Industry reactions came in quickly. Every CEO Dan Shipper offered this assessment: “It’s the strongest coding model we’ve used, but now it’s fast, token-efficient, and crucially actually speaks like a normal person.” The quote highlights not just coding capability but also the naturalness of the response tone. Box CEO Aaron Levie added that Fable 5.1 caught the subtleties and ambiguities in data that Fable 5 had missed in the same test.

    Analysis channel Lisan al Gaib noted that Mythos 5.1’s lower reasoning mode scored on par with the previous model’s maximum reasoning mode. This signals that Claude 5.1’s reasoning efficiency has been significantly elevated.

    The element I find most significant in the Claude 5.1 announcement is the appearance of the term “cache fee.” It signals that model price competition is moving beyond per-token pricing into operational cost structures such as caching, routing, and reprocessing. The timing—coinciding with the case covered in Wired’s report on OpenAI’s hold on disclosing Astra’s cyber capabilities—is also impossible to ignore. It reads as part of a broader trend among major model companies recalibrating the balance between safety frameworks and release procedures.

    What stands out from a practitioner’s perspective is that the magnitude of the price cut varies by workload. Without first classifying your own call patterns before adopting Claude 5.1, you could be dazzled by the “up to 45%” figure and overestimate the actual savings. Pipelines with higher cache hit rates will see gains closer to the upper bound.

    Comparison Item Fable 5.1 Mythos 5.1
    Price reduction 25% for general tasks, up to 45% for agentic Disclosed separately (same cache fee structure presumed to apply)
    Safeguard direction Refined (relaxed blocking for routine biology questions) Biology domain restrictions maintained
    Accompanying release — Project Glasswing
    Initial external evaluation Improvements in both coding capability and response tone (Dan Shipper) Lower reasoning mode on par with previous model’s maximum reasoning mode (Lisan al Gaib)
    Suitable domains Routine coding, documents, and multi-turn agents Biology, medical research, and other domains with strict safety guidelines

    Practical Application Points

    Teams running agentic workloads need to reclassify their call patterns by “cache hit rate.” Even with the same model, pipelines that lean more heavily on cache utilization will see gains closer to the 45% savings mark. If most calls are one-off, the 25% reduction becomes the practical upper limit. The best way to minimize the risk from the safeguard changes is to pre-divide domains that require Mythos 5.1—such as biology and medical research, where safety guidelines are strict—from those suited to Fable 5.1. Finally, it’s advisable to bundle the OpenAI Astra capability-disclosure holdback case together with your own product’s release criteria review materials.

    What to Do Right Now

    • Calculate the cache hit rate from your current API call logs and simulate the savings from adopting Claude 5.1.
    • Separate your model mapping so that biology and medical domain workloads route to Mythos 5.1, while coding and document tasks route to Fable 5.1.
    • Add regression tests for response tone and instruction-following rate to your coding agent’s internal evaluations to compare before and after applying Claude 5.1.
    • Document the OpenAI Astra cyber capability disclosure holdback case in your team wiki to revisit your own product’s capability disclosure criteria.
    • Review your cache TTL and prefix structure to identify room for improving hit rates.

    Frequently Asked Questions

    What is the biggest change in Claude 5.1?

    The core is a structural change: by removing fees on cache data, prices have dropped approximately 25% for general tasks and up to 45% for complex agentic work. What makes it significant is not the discount magnitude itself but the fact that the provider directly revised cache fees—an operational cost line item—rather than offering a simple discount.

    What is the difference between Fable 5.1 and Mythos 5.1?

    Fable 5.1 refined its safeguards to lower the blocking probability for routine biology questions, while Mythos 5.1 maintains the biology domain restrictions unchanged and was released alongside Project Glasswing. It amounts to a dual policy unveiled on the same day.

    Is the reduction effect the same for agentic workloads?

    No. According to the announcement, savings widen to up to 45% for agentic tasks, and pipelines with higher cache hit rates benefit more. If your calls are mostly one-off, the 25% reduction becomes the practical upper limit.

    How does this relate to the OpenAI Astra case?

    Read alongside OpenAI’s hold on disclosing Astra’s cyber capabilities, it can be interpreted as a broader trend in which major model companies are redesigning the balance between capability disclosure and safety frameworks. Claude 5.1’s domain-specific safeguard separation fits the same context.

    Reference Source

    This article was prepared after reviewing the following source: The Verge — Anthropic launches Claude Fable 5.1 and says it’s up to 45 percent cheaper for agentic work

  • Apple CEO Change Confirmed for the First Time in 15 Years — 3 Key Battles Ahead of the September 9 iPhone Event

    Apple CEO Change Confirmed for the First Time in 15 Years — 3 Key Battles Ahead of the September 9 iPhone Event

    Apple CEO Change
    Apple CEO Change: First Leadership Transition in 15 Years, from Tim Cook to John Ternus

    Key Summary

    • Tim Cook stepped down as Apple CEO on September 1, and former hardware chief John Ternus officially took over as his successor.
    • John Ternus, formerly VP of Hardware, is known for having overseen Apple’s hardware business internally for many years.
    • Johny Srouji has been appointed as the new Chief Hardware Officer (CHO), taking charge of the entire hardware lineup.

    Analytical — An industry analysis examining the managerial and political legacy Tim Cook’s 15-year era left at Apple, and the environmental and strategic challenges facing new CEO Ternus, a hardware expert

    Table of Contents

    Apple’s CEO change was officially confirmed on September 1. Tim Cook concluded his 15-year tenure as CEO, and former VP of Hardware John Ternus officially took the helm. The most significant variable is that the decision came just 8 days before the September 9 iPhone event.

    What caught this writer’s attention was the timing of the announcement. Cook had a tradition of not stepping aside right before a product event, and even this time it is highly likely that Ternus himself will lead the event. The very image of the hardware roadmap lead taking the stage is itself a message. This Apple CEO change is, in effect, a replacement of Apple’s identity.

    Apple CEO Change: What Tim Cook’s 15 Years Left Behind

    Cook, who took the seat as Steve Jobs’s successor in 2011, grew Apple into a multinational corporation. Market capitalization, which stood at $350 billion at the time of his appointment, surpassed $3 trillion, and the share of services revenue climbed from single digits to the mid-20% range. Systematizing share buybacks and dividend policy was also his hallmark.

    However, during the same period, as the share of Chinese production rose, a new dependency grew. Apologies over forced labor reports and censorship demands were repeated, and criticism from human rights groups was sharp. The answer Apple chose between supply chain efficiency and values was, in effect, a retreat. This shadow will continue to weigh at the next CEO change as well.

    Cook’s Diplomatic Tightrope — How It Worked and Its Limits

    Cook is known as the figure who moved directly between the Trump administration and Chinese President Xi Jinping. Through repeated visits to the White House and meetings with Chinese officials, he eased tariff shocks and the threat of App Store removal. As seen in The Verge’s coverage, the prevailing assessment is that this diplomatic line was effective in the short term.

    From an operational standpoint, what stands out is the sustainability of this approach. A strategy that depends on one CEO’s personal network does not transfer intact to a successor. The question of whether Ternus holds the same trust from both the White House and Chinese officials is already being raised in the market.

    Who Is Ternus — Strengths and Limits of an Internal Hardware Pick

    John Ternus is an internal hardware expert who has led the Mac, iPhone, and iPad lineups since joining in 2001. He is known as a figure who brokered compromises between chip design and industrial design. At a time when the AI chip architecture race is accelerating, the fact that the person who knows Apple’s silicon roadmap better than anyone is now sitting in the CEO seat carries significant meaning.

    Johny Srouji was simultaneously appointed as the new Chief Hardware Officer (CHO). It was the first personnel decision immediately after the Apple CEO change. Given that both figures come from a hardware background, it is read as a signal that the coming years will place greater weight on internal solidity than external expansion.

    Three Key Battles in the Ternus Era

    Issue Cook Era Ternus Era Challenge
    China Supply Chain Deepened dependence, partial India diversification Accelerate India/Vietnam share
    AI Competition Apple Intelligence late entry On-device model differentiation
    Regulatory Environment Defensive response to Digital Markets Act Redesign App Store revenue structure

    Supply chain must be addressed first. India’s production share has risen to the 15% range, but dependence on China is still close to half. If additional U.S. tariffs are imposed, prices and margins will take a direct hit.

    AI is even more urgent. Apple Intelligence in the Cook era was a late entrant, and on the generative AI battlefield it was categorized as a backmarker. a16z raising $9.6 billion in just 4 days shows how rapidly capital is flooding into the AI value chain. The key question is how far Apple can catch up, leveraging its in-house chips and OS integration as weapons.

    Regulatory pressure is no small matter either. The EU Digital Markets Act and U.S. antitrust lawsuits are proceeding simultaneously, and the App Store commission model is the biggest sticking point. If this structure is shaken, it will directly affect services revenue.

    What the Apple CEO Change Means: The End of ‘Buffer Management’

    Cook’s management style was close to ‘buffering.’ A way of delivering results without antagonizing any stakeholder. Ternus is different. He is someone who solved problems inside the product, and he is likely to seek answers from the internal roadmap rather than external socializing. The Apple CEO change also means a change in management style.

    The first answer will come from the iPhone unveiled on September 9. The very fact that a hardware-focused executive is sitting in the CEO seat is a signal that Apple is trying to redefine itself. This Apple CEO change is not a simple personnel move, but the starting point for designing the next ten years.

    Key Issues Summary

    The Apple CEO change is not a mere personnel swap, but a shift in management paradigm. First, it remains to be seen whether Cook’s ‘endure through diplomacy’ approach will work the same way in the Ternus era. Second, if Apple cannot leverage its chip-OS integration advantage in the AI race, it will be hard to escape its late-mover disadvantage. Third, the speed of India/Vietnam supply chain diversification will be determined by tariff policy and regulatory timelines. Lastly, the September 9 iPhone event itself is Ternus’s first credibility test as CEO.

    What to Do Right Now

    • Check the Apple IR page for the September 9 event livestream in real time, and compare post-announcement stock prices with supply chain partner trends immediately after the new product lineup is unveiled.
    • Track the latest earnings of partners most sensitive to shifts in India/Vietnam production share under different tariff scenarios (Foxconn, Pegatron, etc.).
    • Check Apple Developer documentation directly for Apple Intelligence on-device Korean language support timelines, and note areas applicable to your own services.
    • Monitor EU Digital Markets Act and U.S. antitrust progress on a weekly basis, and incorporate the possibility of App Store commission changes into your scenarios.

    Frequently Asked Questions

    Why is Apple changing its CEO?

    At the point where Tim Cook had served as CEO for 15 years, the company determined that a next-generation leadership transition was necessary. The company assessed that Ternus, an internal executive who has directly led the hardware roadmap, is well-suited to continue product-centric management.

    Who is John Ternus?

    He is a hardware expert who joined Apple in 2001 and led the Mac, iPhone, and iPad lineups. He is known as the figure who coordinated the M-series chips and the silicon transition internally, and he has now taken over as Tim Cook’s successor.

    Where does Tim Cook go after the CEO change?

    As of now, no official successor role has been announced. Advisory roles such as Chairman of the Board are being mentioned, but the company has not yet disclosed a specific position.

    What will be announced at the September 9 iPhone event?

    A new iPhone lineup and Apple Watch updates are most likely. As it will likely be the first event where CEO Ternus takes the stage himself, it is expected to be a moment that reveals his product philosophy.

    Reference Source

    This article was prepared after reviewing the following source: The Verge — John Ternus takes over as Apple’s new CEO

  • a16z Growth Fund Expands to $8.5B — $9.6B Raised in 4 Days Signals Full-Stack AI Value Chain Play

    a16z Growth Fund Expands to $8.5B — $9.6B Raised in 4 Days Signals Full-Stack AI Value Chain Play

    a16z Growth Fund

    Key Takeaways

    • a16z has expanded its fifth growth fund to $8.5B.
    • The expansion adds $1.75B to the $6.75B raised when the fund launched in January.
    • Just days earlier, a16z also officially announced the formation of a new AI-hardware-dedicated vehicle, the “Machine Age Fund,” at $1.1B.

    We unpack what it means for a16z to deploy two mega-funds in rapid succession. By splitting capital into a growth fund (software and services) and a Machine Age Fund (AI hardware), the firm is effectively declaring a play to absorb the entire AI value chain at once. Combined with its January $15B fund, this capital momentum has propelled a16z into the $90B AUM era—all set against a US election backdrop in which lobbying and political spending are being mobilized alongside investment activity. We triangulate these threads to surface what they signal for US VC capital flows in H2 2026.

    The a16z growth fund has swelled to $8.5B. It stood at $6.75B at launch in January, meaning an additional $1.75B was stacked on just seven months after inception. It is the second major capital raise, coming on the heels of the $1.1B “Machine Age Fund” unveiled a few days prior. In practical terms, $9.6B landed in a16z fund accounts over four days.

    The most meaningful signal in this news, in my view, is that a16z has broken from its old pattern of covering AI through a single fund and has clearly separated the growth fund from the Machine Age Fund. $8.5B focused on software and services, plus $11B—wait, $1.1B—dedicated to chips, memory, networking, and storage. Launching two parallel pools of capital from the same firm in the same season is, in effect, a declaration of intent to absorb the entire AI value chain simultaneously.

    The $8.5B a16z Growth Fund: Who Is Running It?

    The general partner leading this a16z growth fund is David George. His team has invested in more than 100 companies over the past seven years. This is not simply a “big fund”; it is capital run by a team with a track record—a structural condition that makes it easier to win the trust of both founders and LPs.

    Where will the extra $1.75B flow? a16z has outlined six deployment areas: enterprise AI, consumer AI, defense tech, robotics, infrastructure HW/SW, and healthtech. That is a coordinate system that touches nearly every frontier industry. In effect, a16z has sent a Silicon Valley message of “we are buying all of AI,” backed by the size of its growth fund.

    From a practitioner’s seat, what stands out is the likelihood that a16z has lifted check sizes by 30–50% over prior norms. It reads as a signal that Series B and later rounds will be written at $100M–$300M ticket sizes. Even as the Hugging Face hack inflates AI-safety concerns, large capital is moving more aggressively, not less.

    The $1.1B Machine Age Fund—The Strategic Meaning of an AI-Hardware-Only Vehicle

    The $1.1B Machine Age Fund is a vehicle dedicated exclusively to AI hardware. True to its name, a16z has carved out a separate pool of capital to invest in “the age of machines.” Rather than tucking chips, semiconductors, and storage into a general growth fund, it has spun them out into a standalone vehicle. This reads as a signal that the firm wants more sophisticated LP reporting and decision-making around hardware bets.

    As the AI industry broadens beyond a model-and-software monoculture into inference infrastructure, on-device AI, and data center power and cooling, a16z has reshaped its fund structure to match that shift. According to the original TechCrunch report, this fund targets startups in chips, memory, networking, and storage.

    Follow-On to January’s $15B Fund—The Capital Engine of the $90B AUM Era

    These two new funds are the follow-on to the $15B in new fund commitments a16z announced in January. As of January, a16z’s assets under management stood at $90B. Single-firm AUM of that scale is rare in US venture.

    What makes that scale possible is the structural reality that growth-stage AI companies are absorbing more capital at higher valuations. Series D and later rounds in 2024–2025 settled into a $100M–$500M base size, and that demand required mega-funds to underwrite. a16z has vacuumed up capital to match that demand with precision. The January raise, which included the a16z growth fund, was the starting gun; the two August funds confirm the pace.

    The Dual Track in an Election Year—Fund Expansion and Political Lobbying

    a16z has also been deploying large sums on political lobbying during this US election cycle. Beyond investing, the firm is moving to exert direct influence on regulatory and policy formation. Co-founders Marc Andreessen and Ben Horowitz have activated policy networks timed to the election cycle.

    This mobilization of political capital is not a CSR exercise; it is a hedge to determine what regulations the fund’s defense, robotics, and AI portfolio companies will face over the next four years. As outlined in the seven pressure points from the Trump administration, US political terrain can reshape the operating environment for VCs itself.

    The Signal Left on the Industry—US VC Capital Flows in H2 2026

    The ripple effects on other VCs are large. The most direct signal is that mega-funds capable of underwriting AI growth are now the standard. Growth funds under $5B are increasingly likely to be classified as laggards.

    The second signal is the separation of hardware funds. The strategy of splitting AI investing across multiple funds by layer—rather than one large pool—is highly likely to be adopted soon by other mega-VCs such as Sequoia and Coatue.

    The third is the normalization of political lobbying. VCs are beginning to view lobbying not as a seasonal event but as part of fund operations. This affects startup regulation, export controls, and AI-safety legislation across the board.

    Issues at a Glance

    • The a16z growth fund was increased by $1.75B—from $6.75B to $8.5B—and combined with the $1.1B Machine Age Fund unveiled days earlier, $9.6B in capital flowed in within four days.
    • Built on the David George team’s seven-year track record of 100+ investments, the a16z growth fund will be deployed across six areas: enterprise AI, consumer AI, defense, robotics, infrastructure, and healthtech.
    • The Machine Age Fund is dedicated to AI hardware—chips, memory, networking, and storage—reflecting a structural choice to run hardware investments separately from software.
    • Adding January’s $15B fund to these two new vehicles pushes a16z into the $90B AUM era, while a dual track of political lobbying during the US election cycle is now visible.

    What to Do Right Now

    • Within a week, confirm the official partner lists for the a16z growth fund and the Machine Age Fund, and classify whether your company in the chip, memory, or storage layer is a potential target.
    • Track David George’s 100+ investment portfolio on Crunchbase to calculate the check sizes and valuation bands the a16z growth fund prefers.
    • Cross-reference the 2026 US election calendar with a16z’s public lobbying disclosures, and draft three scenarios for regulatory change in defense and robotics over the next six months.
    • In one sentence, identify which of a16z’s six investment areas your AI product falls into, and self-assess whether you are at a stage to raise a $100M–$300M round.
    • Watch for the possibility that competitor VCs Sequoia and Coatue will launch their own AI-hardware-only funds, and rebuild your pitch deck in time for that moment.

    Frequently Asked Questions

    How much did the a16z growth fund increase by exactly?

    It launched in January 2026 at $6.75B and, as of late August of the same year, was expanded by $1.75B to a total of $8.5B—an increase seven months after launch.

    How is the Machine Age Fund different from a general fund?

    $1.1B has been raised exclusively for AI-hardware startups—chips, memory, networking, and storage. The key distinction is that the operating lineup and decision-making structure have been separated from the software-and-services-focused a16z growth fund.

    What is a16z’s total assets under management?

    AUM stood at $90B as of January 2026. Adding the January $15B fund plus these two new vehicles is expected to bring total AUM close to $100B.

    What does this fund expansion mean for the average founder?

    Round sizes at Series B and later are likely to standardize at $100M–$300M. With larger checks comes greater pressure on pre-money valuations, so pulling forward the timing of a fundraise becomes advantageous.

  • Apple vs. OpenAI Trade Secret Lawsuit: Three Key Clashes — “Shocking Evidence” vs. “Residual Access” Explanations

    Apple vs. OpenAI Trade Secret Lawsuit: Three Key Clashes — “Shocking Evidence” vs. “Residual Access” Explanations

    Apple OpenAI

    Key Summary

    • Apple has submitted new materials to the court, described as “shocking evidence,” in its lawsuit against OpenAI.
    • The central defendant in the lawsuit is former Apple employee Chang Liu, who is now employed at OpenAI.
    • Liu’s old company-issued MacBook was handed over to investigators through his attorneys, and this process uncovered new evidence.

    Analysis

    More than two months after the trade secret lawsuit between Apple and OpenAI was filed in June, the case has entered a new phase. In a recent court filing, Apple used the expression “shocking evidence” and pointed out that former hardware engineer Chang Liu used the company’s confidential circuit schematics while working at OpenAI. While the publicly available materials do not establish the full facts, the two sides’ claims are directly at odds.

    The Facts — What One MacBook Revealed

    Liu worked in Apple’s hardware engineering division before leaving to join OpenAI. The newly obtained material in this Apple vs. OpenAI dispute is Liu’s old company-issued MacBook. Once this MacBook was handed over to investigators through his attorneys, traces of schematic usage and records of tools sharing the same names as internal engineering applications were uncovered. An expression I find noteworthy is Apple’s statement that “the MacBook provided only extremely limited information from the defendant’s side.” Rather than a simple fishing expedition, this reads as an intent to prove that trade secrets were actually used and destroyed.

    Evidence from Both Sides in Apple vs. OpenAI — Schematics, Identically Named Tools, and Destruction Attempts

    According to court materials, Liu is alleged to have used Apple’s circuit schematics in his work at OpenAI. Traces of tool usage sharing names with internal engineering applications were also discovered. Additional allegations claim that, after learning of Apple’s investigation in June, Liu engaged in evidence destruction efforts together with his OpenAI colleague Yu-Ting Peng. The disclosed message records include exchanges in which Liu, while knowing he still had access to Apple files, sent a “laughing through tears” emoji. In other words, he was aware that his access was still active and wrapped it in humor.

    How Far Does OpenAI’s “Residual Access” Explanation Hold Up?

    OpenAI countered that Liu simply responded to a former colleague’s request for help accessing files after his departure — the so-called “residual access.” In the Apple vs. OpenAI lawsuit, OpenAI emphasized that this is a universal problem stemming from Apple’s poor system management. In other words, the framing is that this was not Liu’s intentional act but rather the result of the company’s inadequate off-boarding procedures. The premise is that Liu cooperated with a legitimate request from a former colleague at the company he had left.

    Apple’s Direct Counter — Why the “Rare Authentication Bug” Argument Carries Weight

    Apple countered with the assertion that Liu “exploited a rare and previously unknown authentication bug” to maintain access. This is the claim that, rather than typical residual permissions, there was a deliberate and technical bypass attempt. If this portion is established as fact, not only Liu but also OpenAI’s knowledge of the matter will come under new scrutiny. From a practitioner’s perspective, what stands out in the Apple vs. OpenAI lawsuit is that while both sides use the word “facts,” the scope each side points to is entirely different.

    Summary of Key Issues

    The case converges around four main issues. First, whether the circuit schematics meet the trade secret requirements (non-disclosure, economic value, and reasonable protective measures). Second, whether Liu and Peng’s actions rise to the legal threshold of “evidence destruction.” Third, whether OpenAI was aware of or actively participated in this matter. Fourth, how much responsibility Apple itself bears for off-boarding system controls.

    Among these, the part I find most significant is the third. If OpenAI fails to prove the specific point at which it became aware — beyond the general claim that “residual access is a universal problem” — confidence in hiring-stage due diligence could be shaken.

    Apple vs. OpenAI-Style Disputes Spreading Across the AI Industry

    This Apple vs. OpenAI lawsuit is not an isolated case. Since 2024, as AI talent mobility has surged, trade secret disputes have become a structural issue in the U.S. IT industry. The EU has also recently designated ChatGPT as a VLOP, strengthening the responsibility of large AI platforms within the EU DSA regulatory flow. In the EU’s first application of AI regulation to ChatGPT, standard competition and responsibility also emerged as core issues. This article was written primarily based on TechCrunch’s August 31 article.

    There are three variables in the upcoming proceedings: when and in what form Apple will disclose additional evidence; whether OpenAI will submit additional counter-filings; and how this case connects with other former employees who have moved to OpenAI like Liu. The essence of the Apple vs. OpenAI conflict is not a single lawsuit, but the question of where to draw the new compliance standard for the age of AI talent mobility.

    Actions to Take Right Now

    • Audit departing employee account permission revocation logs on a 90-day cycle.
    • Record file access requests sent by former colleagues of departing employees as a separate audit item.
    • Create a comparison table listing internal engineering tools and externally shared tools.
    • Run a dry-run to verify that all access permissions are deactivated within 24 hours of a departure notice.
    • Obtain a written acknowledgment of compliance with the previous employer’s trade secret policy when recruiting talent.

    Frequently Asked Questions

    Who is the defendant in the Apple vs. OpenAI lawsuit?

    The defendant is former Apple hardware engineer Chang Liu. Liu joined OpenAI immediately after leaving Apple, and Apple claims its trade secrets were leaked in the process.

    What exactly is the “shocking evidence”?

    According to Apple’s court filing, the company MacBook and communications of Liu revealed circuit schematics used in OpenAI work, traces of tool usage sharing names with internal applications, and evidence destruction attempts.

    How has OpenAI countered?

    OpenAI argued that Liu’s access was merely a response to a former colleague’s help request after his departure, and that “residual access” is a universal phenomenon arising from Apple’s poor system management. Apple countered head-on with the characterization of “exploitation of a rare authentication bug.”

    What are the implications of this case for the AI industry?

    As AI talent mobility has intensified, trade secret disputes have been structurally increasing. This is likely to become an occasion for both hiring-side due diligence obligations and departing-side off-boarding control responsibilities to be recalibrated together.

  • EU AI Regulation: 4 Key Issues in Its First Application — The Standards Race Triggered by ChatGPT’s VLOSE Designation

    EU AI Regulation: 4 Key Issues in Its First Application — The Standards Race Triggered by ChatGPT’s VLOSE Designation

    Key Summary

    • OpenAI’s ChatGPT has been officially classified as a ‘Very Large Online Search Engine (VLOSE)’ under the EU Digital Services Act (DSA)
    • The DSA mandates systemic risk assessments, transparency reporting, and independent audits for very large platforms and search engines with 45 million or more monthly active users in the EU
    • OpenAI must demonstrate concrete mitigation measures across four areas: ① Minor protection (strengthening safety guardrails against self-harm and suicidal ideation), ② Mental health (detecting and intervening in dependency or psychologically harmful conversation patterns), ③ Illegal content blocking (child sexual abuse material, terrorist content, and intellectual property infringement), and ④ Algorithmic transparency (evaluating the impact of recommendations and model updates and disclosing them to EU users)

    Policy Analysis – An insight column diagnosing the structural impact of the EU’s first generative AI regulation case on global AI industry governance and summarizing the issues the industry must address

    The EU AI regulation has been applied to a generative AI service for the first time. OpenAI’s ChatGPT has been officially classified as a ‘Very Large Online Search Engine (VLOSE)’ under the EU Digital Services Act (DSA). Having surpassed the 45 million monthly active user threshold, and given that users directly leverage model outputs in the form of search, summary, and recommendations, its influence comparable to that of a search engine has been recognized.

    This classification is not mere labeling. Three obligations—systemic risk assessment, transparency report submission, and external independent audit—fall squarely on OpenAI. Although the DSA took effect in August 2024, this is the first time a generative AI service has been designated as a VLOSE. Until now, only Google Search, Microsoft Bing, and Yahoo had held that VLOSE designation.

    What I find noteworthy at this juncture is the ‘expansion of definition.’ The fact that the interpretation including ‘conversational AI responses’ within the search engine category has been formalized. This precedent effectively sets the baseline for the next EU AI regulation case.

    Four Key Areas OpenAI Must Demonstrate

    The European Commission has required concrete mitigation in four areas. First, minor protection. OpenAI must demonstrate that guardrails actively block output patterns that encourage self-harm and suicidal ideation. Second, mental health. Procedures must be in place to detect and intervene in signals that a given user is over-relying on the chatbot—the so-called ‘psychologically harmful conversation patterns.’

    Third, illegal content blocking. A filtering system is required to ensure that child sexual abuse material, terrorism-related content, and intellectual property-infringing content are neither generated nor disseminated. Fourth, algorithmic transparency. The impact of recommendation logic and model updates on output results must be assessed and disclosed to EU users.

    Among these four, the most demanding is the transparency report. This does not mean revealing model weights or training data themselves. However, changes must be documented in a traceable form, showing ‘what was changed and what user impact that change produced.’ Because this is an area where OpenAI has historically preferred non-disclosure, practical conflicts are inevitable. The core of the EU AI regulation lies in this transparency reporting.

    The Enforcement Weapon: 6% of Global Revenue

    The European Commission can issue formal information requests to OpenAI and, if necessary, conduct on-site inspections. If a DSA violation is confirmed, fines of up to 6% of global revenue can be imposed. Based on OpenAI’s approximately $3.7 billion in revenue as of 2024, even a simple calculation yields an enormous amount. Indeed, the DSA fines already imposed on Google and Meta have run into the billions of euros.

    The scenario most discussed in the industry is ‘EU market functionality reduction.’ This is because regulatory avoidance is possible by disabling certain model updates or new features for EU users only. Meta has, in fact, made similar choices regarding its News tab features. This is the backdrop for speculation that a ‘EU-only lite version’ of generative AI services could emerge.

    Spillover to Competing Models and Global Ripples

    The ripple effects of this EU AI regulation application extend beyond OpenAI. Google Gemini, Anthropic Claude, and xAI Grok also stand before the same logic. Any service with more than 45 million EU users cannot escape VLOSE classification. Considering the ongoing trend of Google Search integrating with Gemini, Gemini’s VLOSE designation is only a matter of time.

    Other jurisdictions—Brazil, the UK, and Korea—are also highly likely to adopt the EU AI regulation case as a de facto reference standard. With the EU AI Act simultaneously advancing its regulation of high-risk AI systems, generative AI providers must bear a dual regulatory framework of the DSA and the AI Act. This creates a pace of EU AI regulatory standardization distinct from markets like the United States and China, which move under single federal regulation.

    From a practitioner’s perspective, what stands out is that the competition over regulatory standards has been re-ignited on top of the aging category of ‘search engine.’ In an era where AI generates information, regulatory authorities across countries have entered a full-scale tug-of-war over how to define the ‘intermediary of information.’ Governance discussions at the data infrastructure level have already been addressed in the Semantic Architecture: 3 Core Axes Analysis.

    This EU AI regulation decision has effectively become the starting point of a global de facto standard. Subsequent jurisdictions are likely to copy this case wholesale, and every AI provider considering entry into the EU market must pass this benchmark. The EU AI regulation standard is highly likely to solidify as the benchmark. Further details can be verified in The Verge’s report on OpenAI ChatGPT and the EU DSA.

    What to Do Right Now

    • Audit the monthly active user count of your EU-targeted services in the 44.5–45 million range and simulate when you might cross the VLOSE threshold.
    • Establish an internal logging system that automatically records model update history alongside user impact assessment items.
    • Draft 10 risk scenarios related to minors and mental health, and document blocking and intervention procedures for each.
    • Build a legal and compliance hotline capable of responding to European Commission information requests within 72 hours.
    • Institutionalize a quarterly governance meeting where technology, legal, and product teams jointly review plans to limit features in the EU market.

    Key Issues Summary

    • Definition Debate: The European Commission’s interpretation of whether AI responses fall within the scope of ‘search engine’ will set the baseline for all future generative AI regulation.
    • Dual Burden: DSA VLOSE obligations and EU AI Act high-risk AI obligations apply simultaneously to the same provider, potentially increasing compliance costs geometrically rather than linearly.
    • Market Fragmentation: An EU-only reduced version—the ‘regulatory dark age’ strategy—is likely to become a new global SaaS standard.
    • Standards Race: If subsequent regulators in Brazil, the UK, and Korea effectively adopt the EU case as their benchmark, a global de facto EU AI regulation standard will solidify.

    Frequently Asked Questions

    What is a VLOSE?

    A Very Large Online Search Engine as defined by the DSA, referring to services with more than 45 million monthly active users in the EU. Once designated, systemic risk assessment, transparency reporting, and external audits become mandatory.

    Why was ChatGPT classified as a search engine?

    The pattern of users directly leveraging ChatGPT’s responses for information search, summary, and recommendation has grown, and the user base exceeded the DSA threshold. The European Commission deemed this comparable to search engine functionality.

    What is the maximum fine that can be imposed on OpenAI?

    If a DSA violation is confirmed, up to 6% of global revenue can be imposed. Even based on OpenAI’s approximately $3.7 billion in 2024 revenue, this would amount to a massive sum.

    Will Google Gemini and Anthropic Claude face the same regulation?

    If their EU user base exceeds the threshold, they will face the same VLOSE regulation. Given the trend of Gemini integrating with Google Search, its designation is highly likely.